CONTACT US: 0919 058 5858 | 02 899 51920
CONTACT US:
0919 058 5858 | 02 899 51920
“Healthy naman ako ngayon.” Many Filipinos say this familiar line, often to justify putting off health protection. When nothing seems wrong, it’s easy to focus on other things. But taking care of your health isn’t just about addressing problems when they arise. It’s also about having peace of mind and being prepared for the unexpected.
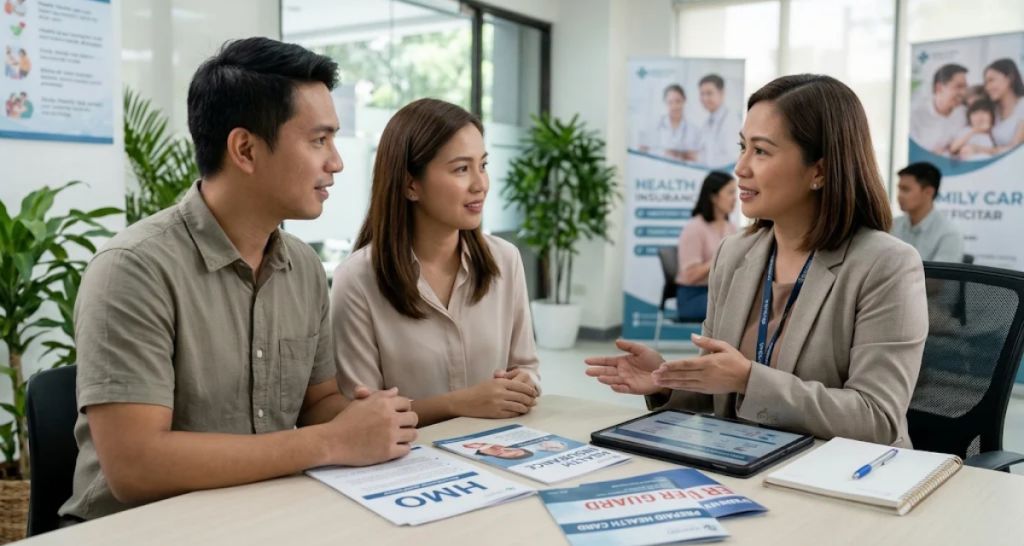
Investing in health protection while you’re young and healthy usually means lower premiums. Pre-existing health conditions may not be covered by some types of health protection. If you’re not suffering from any health conditions, you can be protected for certain future health issues, depending on the terms of your policy.
Health protection comes in different forms, including health insurance, HMO, and prepaid health cards. Understanding how these options work can help you make a more informed decision about the kind of health protection that suits your needs, lifestyle, and budget.
Health insurance is a policy that provides financial coverage for some or all medical expenses, depending on your plan. The Philippine Health Insurance Corporation (PhilHealth) is an example of health insurance. However, this government-run health insurance may not be enough to cover all medical expenses.
Private health insurance usually has more flexible coverage compared to HMOs. You can purchase health insurance for yourself, an individual family member, or your entire family under a family health plan.
Depending on your health insurance, you may have the freedom to choose your own doctor and hospital. Coverage may include consultations, laboratory tests, emergency care, and hospitalization. Certain health insurance plans may provide financial assistance if you get diagnosed with critical illnesses like heart attack, stroke, or cancer. Some policies provide a lump-sum benefit that can be utilized for treatment and recovery.
HMO is another type of health insurance that may offer a range of services such as routine check-ups, preventive care, diagnostic procedures, emergency care, hospital confinement, and other medical services. It usually requires an annual premium and is valid for a fixed, renewable period.
Most big private companies provide HMO for their employees, but coverage usually ends when an employee leaves the company. Self-employed and freelancers can apply for one voluntarily. Medicare Plus Inc. offers high-quality and affordable HMO Philippines that fit the needs and budget of many Filipinos. We have Individual, Family, and Corporate Plans with varying coverage. Each HMO plan generally includes inpatient, outpatient, and preventive health care. It can be used several times during the coverage period, subject to the maximum benefit limit (MBL).
As a top-rated HMO provider in the Philippines, our plans provide members with convenient access to healthcare services in private hospitals around the country. Knowing that you have healthcare coverage can give you greater peace of mind. You can seek medical attention when needed without worrying as much about the cost of every consultation or procedure.
A prepaid health card is an affordable healthcare product that requires only a one-time payment. It provides specific medical coverage that you can avail of within a fixed validity period. Unlike a traditional HMO, a prepaid health card doesn’t have monthly premiums or recurring payments.
ER Guard, the best prepaid health card Philippines, is dedicated for outpatient emergency care. For an affordable one-time fee of ₱970, you can get up to ₱20,000 coverage for eligible emergency treatment. It is valid for one year upon activation. If your medical bills exceed
₱20,000, you pay the remaining balance out of pocket.
If you’re looking for broader coverage, ER Guard Plus may be the ideal choice for you. It features both emergency care and inpatient care for a one-time payment of ₱3,315. ER Guard Plus has a validity period of one year upon activation and provides up to ₱50,000 coverage for eligible emergency treatment and inpatient expenses.
ER Guard and ER Guard Plus are suitable for children (15 days old – 17 years old) and adults (18 to 60 years old). If you’re looking for a health card for freelancers and the self-employed, health card for children, or a health card for young adults, ER Guard and ER Guard Plus offer affordable ways to prepare for medical emergencies. Both prepaid health cards also provide 100% coverage for eligible pre-existing conditions.
Should You Choose Health Insurance, HMO, or Prepaid Health Card? The right type of health protection depends on your healthcare needs, budget, and the level of coverage you want.
You can consider getting an ER Guard or ER Guard Plus prepaid health card if you prefer an affordable health protection with a one-time payment. No need to worry about recurring premiums. A prepaid health card has specific medical benefits that you can avail within a year after activation.
If you’re looking for broader coverage, an HMO generally includes consultations, diagnostics, preventive care, hospitalization, and other healthcare services, subject to a maximum benefit limit. You can choose an Individual or Family Plan, while businesses can explore a Corporate Plan for their employees.
The good news is that you don’t have to limit yourself to just one because you can combine them for comprehensive protection.
You can maximize your health protection by combining PhilHealth and HMO or PhilHealth and Prepaid Health Card. Combining their benefits can help reduce your final medical bill.
With the PhilHealth YAKAP–HMO/PHI Benefit Complementation Initiative, Filipinos are protected from being billed for the same medical expenses by both PhilHealth and private healthcare coverage providers. This gives you a greater value from every peso you spend on healthcare.
1. What is the difference between an HMO and a prepaid health card?
An HMO typically provides a wider range of healthcare services, such as consultations, diagnostic tests, preventive care, and hospitalization, depending on the plan. A prepaid health card offers specific medical benefits for a fixed period, usually for a one-time payment.
2. Does a prepaid health card cover hospitalization?
It depends on the type of prepaid health card. Some cards cover emergency outpatient treatment only, while others include emergency hospitalization or confinement benefits. ER Guard Plus includes emergency outpatient and inpatient care (including the use of ICU, OR, Recovery and Isolation Rooms).
3. Can I have both an HMO and a prepaid health card?
Yes. Having an HMO and prepaid health card can give you additional protection. You can use your HMO for covered healthcare services and your prepaid health card for eligible medical emergencies.
4. Can I use ER Guard multiple times?
No. Each card is intended for one emergency use only. Once utilized, you cannot use it again even if there is an unused balance.
5. Can I buy a prepaid health card for my child or family member?
Yes. ER Guard and ER Guard Plus are available for ages 15 days to 60 years old.
Easy access health plan options for the Filipino community.
We know finding the right healthcare plan can be a complex and confusing task.
Our health plan specialists are always here to help 24/7.
Got more questions?